Business payment card: the ultimate 2026 comparison

In 2026, opening a payment card for your business has never been easier. Virtual cards, adjustable spending limits, cashback, and multi-currency features have become standard. The real question is no longer "who offers a card?" but "which corporate payment card truly fits my usage, my actual international costs, and my commitments?"
This comparison reviews the main players (Qonto, Revolut Business, Pleo, Spendesk, Payhawk, Wise, American Express), the criteria that really matter, and Keewe's position for SMEs and mid-market companies focused on international operations.
What really matters when choosing a business card
Before comparing brands, list your actual usage. Five criteria make the difference in terms of costs and daily operations.
The actual cost of international transactions is the primary hidden expense. Between a card with a real exchange rate and one charging 1% to 3% per foreign currency payment, the annual difference quickly adds up to thousands of euros for a company paying foreign suppliers. Next is team expense management: permissions per employee, real-time limits, single-use cards, and receipt capture. Then comes security (3D Secure, fund segregation, dual-control rules), support (chat, phone, dedicated expert), and finally, a growing criterion: the ability to measure, and ideally finance, the carbon impact of your payments.
The categories of providers
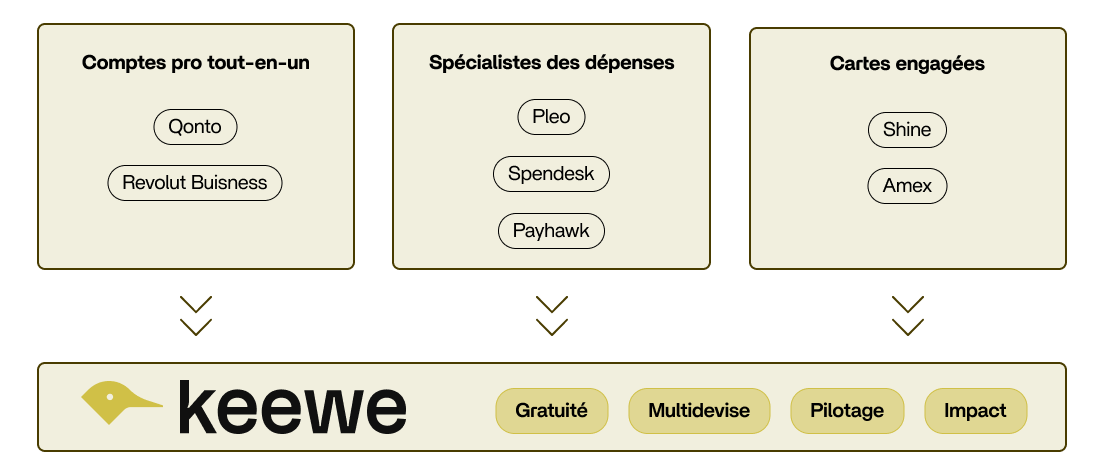
The market falls into three categories. All-in-one business accounts (Qonto, Revolut Business) where the card is linked to a full account. Expense management specialists (Pleo, Spendesk, Payhawk, N2F) that focus on controlling team spending. And committed players (Shine, Keewe) that add an environmental dimension. One category remains separate: the traditional loyalty card (American Express).
Each covers part of the need: some the account, others the expenses, and others international operations or carbon measurement. Only one platform brings these three areas together in one place: Keewe. Before we get to that, let's look at what each player actually offers and where each one falls short.
Qonto
A French all-in-one business account: invoicing, pre-accounting, included Mastercard cards, and virtual/disposable cards. Designed for freelancers, micro-businesses, and SMEs that want to centralize their management in euros. Plans from €9 to €199 excl. tax/month. Cashback is not offered on standard cards, and payments outside the eurozone on the included One card are charged at 2% (plus €2 per withdrawal).
An account designed for euro-based management, not for international flows or impact.
Revolut Business
An international-focused neobank: physical and virtual cards (including single-use), exchange at the interbank rate up to a free monthly limit, and cashback starting from the Grow plan. For companies that perform many foreign currency transactions. Plans from €10 to €90 excl. tax/month. Beyond the exchange limit, a commission applies.
A multi-currency account, without impact measurement or financing.
Pleo
An expense management tool: physical and virtual Mastercards, over 50 currencies, automatic receipt capture, and accounting integrations. For teams that want to automate their expense reports. Cashback (0.5% to 0.75%) is reserved for higher-tier plans and capped at the subscription amount. Plans from €4 to €199 excl. tax/month.
A tool focused on internal expense control.
Spendesk
End-to-end expense management: Visa cards, expense reports, supplier invoices, and approval workflows. For structured finance teams. Pricing by quote only, exchange fees of approximately 1.99% outside the euro, no cashback.
Internal expense control, lacking an international dimension or impact.
Payhawk
Visa debit and credit cards, 0% fees in 7 currencies, transaction cashback, credit lines up to €500,000 without personal guarantees, OCR and ERP integrations, and per-transaction CO2 tracking for ESG reporting. Designed for scale-ups, mid-market companies, and large enterprises (micro-businesses are excluded). Carbon measurement is for reporting purposes only, with no funding for impact projects.
Advanced expense management that measures your footprint but does not fund it.
Wise Business and American Express
Wise: No subscription, one-time fees (€50 to open, €3 per physical card), unlimited virtual cards, and over 40 currencies at the real exchange rate. Ideal for low-cost international transfers; lacks cashback and advanced team expense management. American Express: Annual fees from €95 to €708, deferred debit, and a loyalty program. Focused on rewards and travel; offers low cashback (approx. 0.3%), 2.8% foreign transaction fees, and more limited acceptance.
Comparison table
Data verified from provider websites, current as of July 3, 2026. Rates and terms are subject to change; please verify before signing up.
Looking at the impact column: only two providers show "Yes." One measures emissions for reporting. Keewe is the only one in this comparison that measures and funds impact through the Planet Dividend, at no cost to your company. That is the decisive difference.
Why Keewe is the best choice for your business
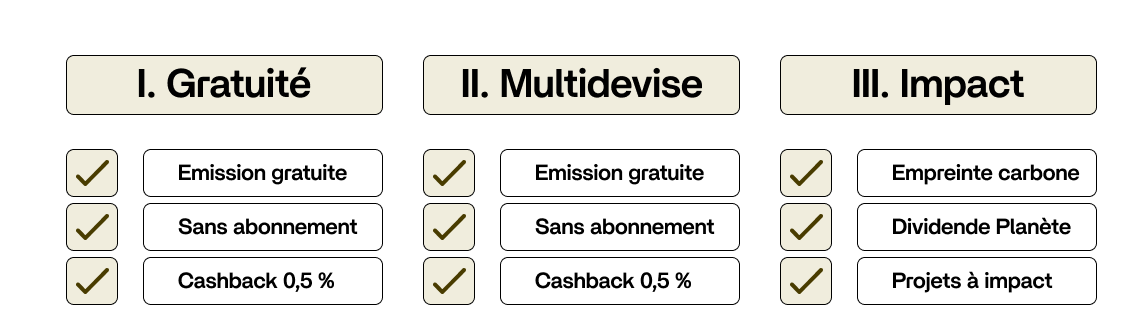
While neobanks stop at basic accounts, expense specialists at internal control, and the most advanced players at simple carbon measurement, Keewe brings together the three pillars that matter.
On the fundamentals, the Keewe VISA virtual card has no issuance fees or subscription costs, with 0.5% cashback on every transaction*—with no strings attached, as there are no plans. It is multi-currency (EUR, USD), allows you to create as many cards as needed, manage permissions and limits per employee, and block payments at any time. Funds are held in a safeguarded account at Barclays via Currencycloud, a Visa group subsidiary, and sensitive operations are governed by the four-eyes principle.
Regarding impact, every transaction automatically calculates its carbon footprint via Impact Payment AI and generates a Planet Dividend that funds impact projects at no cost to your company. Where others stop at measurement, Keewe turns spending into a funded decarbonization lever.
And for international flows, Keewe is more than just a card: it is a platform that combines international payments, foreign exchange risk hedging, and card services, all with dedicated expert support. For a company that pays international suppliers and wants to manage its footprint, it is the balance that others simply do not offer.
Trust signals
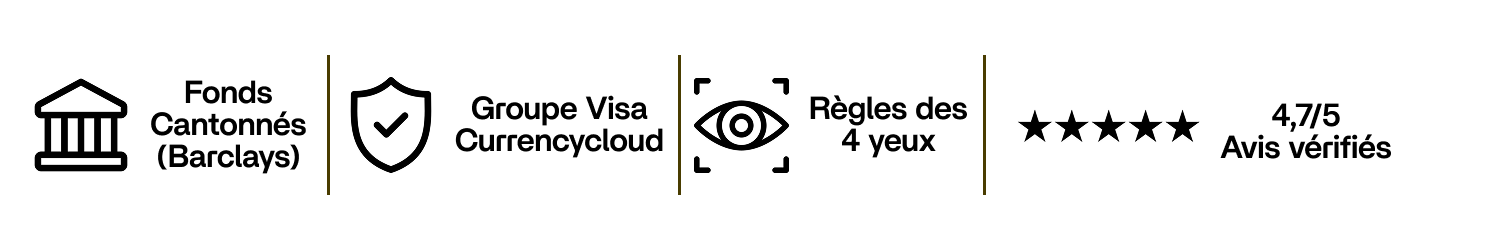
Keewe relies on an infrastructure backed by Barclays and the Visa group, the four-eyes principle, and verified customer testimonials. Michel Gambino (BM Distribution) halved his fees on dollar imports; Renaud Lacoste (Tahe Outdoors) highlights the proactivity regarding currency hedging and the user experience; Pierre-Alexandre Chiron (Planet Ride) secured his prices for the year thanks to a guaranteed rate contract.
How to choose
The right approach isn't to multiply your tools, but to choose one that covers all your needs. A free card, multi-currency support, expense management, the security of an infrastructure backed by Barclays and the Visa group, and a truly measured and funded impact: Keewe brings it all together on a single platform.
To discover the Keewe payment card and tailor it to your needs, visit the Payment Card page or fill out the contact form. 👇
*Valid for the first 12 months.

Pour aller plus loin, découvrez nos derniers articles.
Vous y trouverez les recommandations de nos experts pour gérer vos opérations de commerce international de façon plus durable et responsable.